
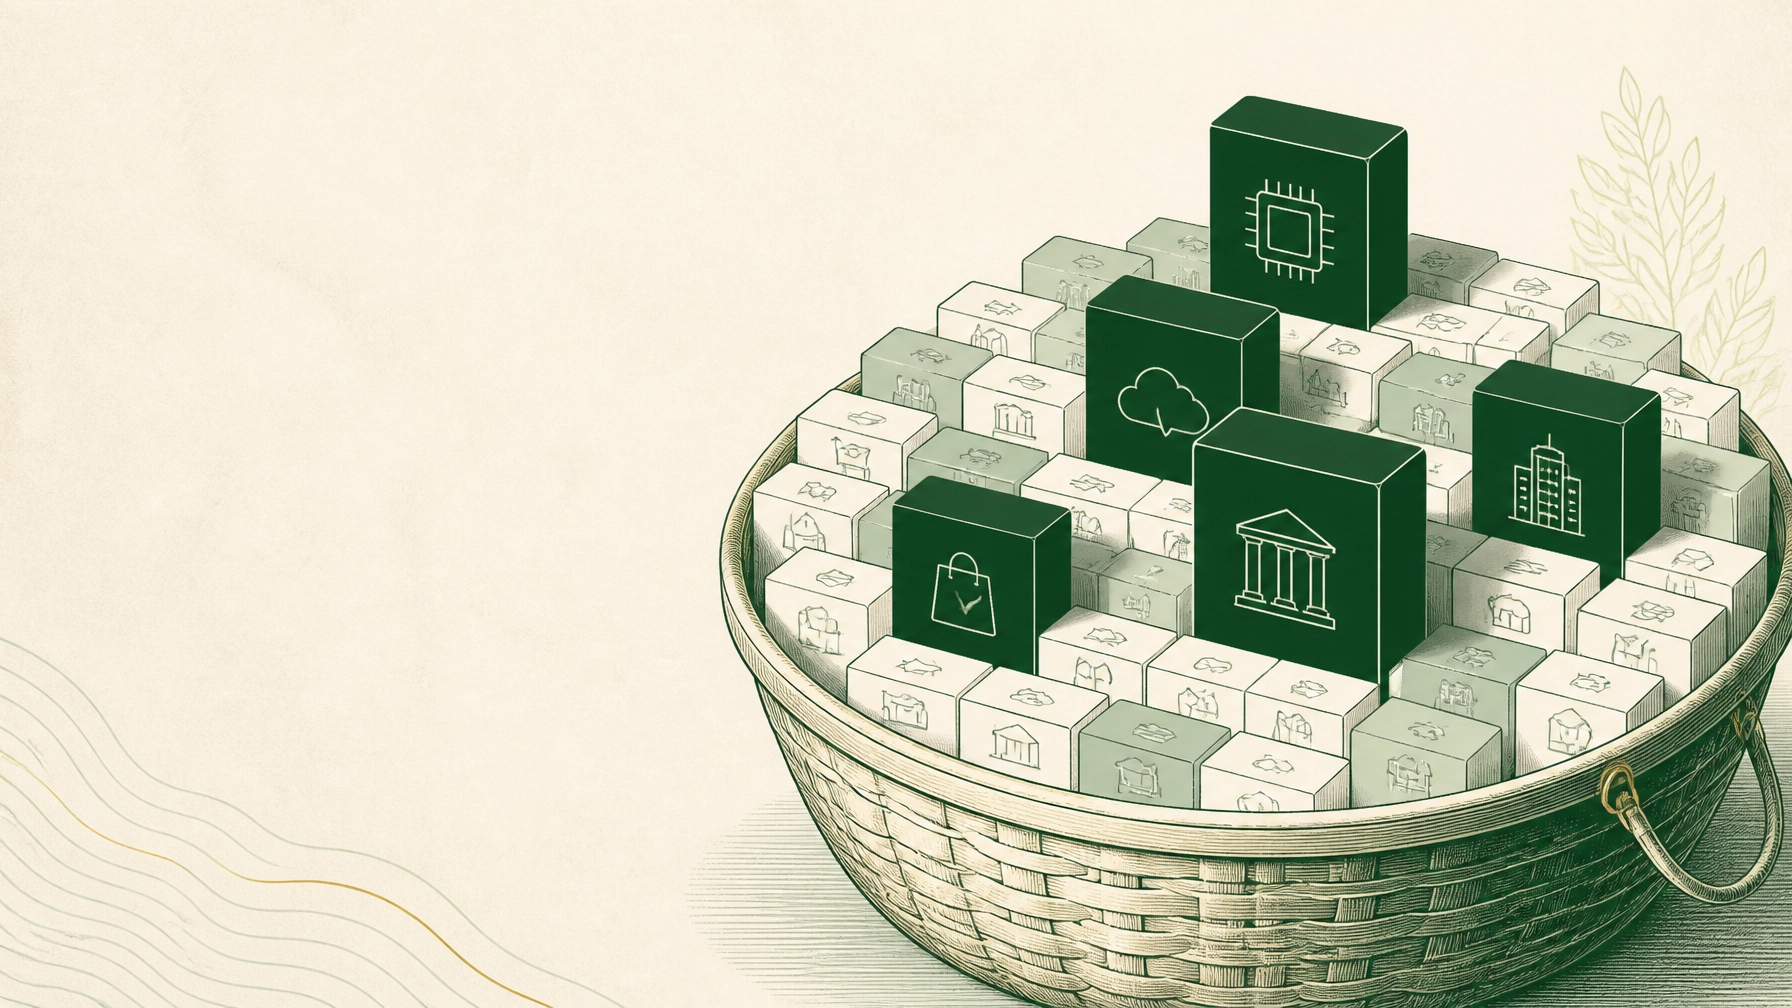
An editorial illustration showing how a fund can hold many investments while still being dominated by a small number of large positions.
A fund that owns hundreds or thousands of companies may appear highly diversified. But the number of holdings does not tell the entire story.
If a broad market fund is weighted by market capitalization, its largest companies receive the largest allocations. When a small group of companies grows substantially, those companies can begin to influence much of the fund’s performance. An investor may own a broad fund, yet still have meaningful exposure to a narrow group of businesses, sectors, or economic themes.
This is known as concentration risk. It is not necessarily a reason to avoid broad market funds. It is a reason to understand what they actually own and how those holdings fit within your complete portfolio.
What is concentration risk?
Concentration risk is the possibility that a portfolio’s results will depend too heavily on a small number of investments, industries, market segments, or other related factors.
Diversification seeks to spread risk across different holdings and sources of return. It can reduce the effect of one company or sector performing poorly, although it cannot eliminate broad market losses.
The SEC’s Investor.gov guidance on diversification emphasizes that diversification involves more than owning multiple securities. Investors should consider exposure across asset classes, industries, companies, and geographic regions.
Concentration can appear in several ways:
- A large percentage of a fund is invested in its top 10 holdings.
- Several funds own many of the same companies.
- A portfolio has an unusually large allocation to one sector.
- Different investments are driven by the same economic theme.
- One position or group of positions contributes disproportionately to portfolio risk.
The important distinction is between breadth and weight. A fund can be broad in the number of companies it owns while still being concentrated in the amount invested in its largest holdings.
Why broad market funds can become top-heavy
Many broad market indexes use market-capitalization weighting. Market capitalization is the total market value of a company’s publicly traded shares.
In a market-cap-weighted index, a company with a larger market value receives a larger index allocation. If the company’s share price rises faster than the broader market, its weight generally increases as well.
The S&P 500 methodology describes the index as float-adjusted market-capitalization weighted. This means the largest publicly traded companies can represent a substantial portion of the index, even though the index includes hundreds of constituents.
The same principle applies to many total-market funds. These funds may include large-, mid-, and small-cap companies, but the largest companies can still account for much of the fund’s total value.
This structure is not necessarily a flaw. Market-cap weighting is transparent, rules-based, and widely used. However, it can create a portfolio that behaves more like its largest holdings than its full list of holdings suggests.

Market-cap weighting gives greater influence to companies with larger market values, which can make a broad fund more top-heavy.
The difference between owning many funds and owning different exposures
Investors sometimes add multiple funds believing that more funds automatically create more diversification. That may not be the case.
For example, a household might own:
- A broad U.S. market fund
- A large-cap growth fund
- A technology-focused fund
- An employer stock position
- A target-date or managed portfolio fund
Each investment may have a different name and purpose. But several may own the same large companies. The result can be overlapping exposure that is difficult to see without reviewing the underlying holdings.
This is called look-through analysis. Instead of evaluating each fund separately, the investor examines the securities held across the entire portfolio.
The goal is to identify the combined exposure to:
- Individual companies
- Business sectors
- Company size categories
- Growth or value characteristics
- Domestic and international markets
- Common economic drivers
Two funds may not have identical holdings, yet still move similarly because they are exposed to the same companies or investment factors.
The FINRA discussion of concentration risk highlights that concentration may result from exposure to the same security, asset class, market segment, or other related investments.
Why concentration matters more near retirement
Concentration risk deserves particular attention as retirement approaches because the portfolio may soon serve two purposes:
- Supporting long-term growth
- Providing money for current spending
A concentrated portfolio can experience larger swings when the companies or sectors receiving the greatest weight fall out of favor. A decline does not automatically mean a long-term plan has failed, but it can create difficult decisions when withdrawals are also required.
Consider a hypothetical investor, Elena, who owns a broad U.S. equity fund in her retirement account. The fund holds hundreds of companies, but its largest positions represent a significant share of its value. Elena also owns a separate growth fund that holds many of those same large companies.
On paper, she owns two diversified funds. In practice, a considerable portion of her equity exposure may depend on the same group of businesses.
If those holdings decline while Elena is withdrawing money, she may have fewer options. She could sell the affected investments during a downturn, reduce spending, use other liquid assets, or revisit the timing of withdrawals. The best response depends on her full financial situation, but the concentration should have been identified before it became urgent.
Five questions to ask when reviewing a broad market fund
1. What percentage is in the top 10 holdings?
A fund’s fact sheet or website typically provides its largest positions. Review both the individual weights and the combined weight of the top holdings.
A fund holding many companies may still have a large share of assets in its biggest positions.
2. Which sectors dominate the fund?
Look beyond individual company names. Several companies may belong to the same sector or depend on similar trends.
A portfolio can be concentrated in a sector even when no single company appears excessive.
3. How much overlap exists among your funds?
Compare the top holdings of each fund. Pay particular attention to positions that appear repeatedly.
You do not necessarily need to eliminate every repeated holding. The objective is to understand the total exposure and decide whether it is consistent with your goals, time horizon, and ability to tolerate volatility.
4. How large are the positions in your complete portfolio?
Position sizing refers to the percentage of the total portfolio allocated to a particular investment or exposure.
A company may represent a modest percentage of one fund but become a much larger percentage after combining several funds and individual accounts.
5. Has the portfolio changed without a deliberate decision?
Market movements can cause portfolio weights to drift. A holding that started at a moderate allocation may become much larger after a period of strong performance.
Periodic review helps distinguish between an intentional allocation and one created by market movement.

Look-through analysis can reveal overlapping holdings that are not obvious from the number of funds in an account.
How to review concentration without chasing headlines
Concentration review should be based on portfolio design, not on predictions about which company or sector will perform best next.
A practical review may include:
- Listing every investment account
- Recording the largest holdings in each fund
- Adding repeated positions together
- Reviewing sector and geographic exposures
- Comparing the current allocation with the intended allocation
- Considering the portfolio’s withdrawal needs and time horizon
- Checking whether the portfolio still reflects the investor’s tolerance for volatility
Investors should also review fund documents carefully. A fund’s prospectus, fact sheet, and shareholder reports can explain its investment approach, risks, and current exposures. Holdings change over time, so a review from several years ago may no longer describe the portfolio accurately.
The Portafolio Capital Management risk analysis page provides additional context on evaluating portfolio risk. Our investment strategy page also explains how portfolio positioning, security selection, and economic indicators may be considered within a broader management process.
The key takeaway
Broad market funds can be useful building blocks, but “broad” does not mean every holding has the same influence.
The most important questions are not simply:
- How many companies does this fund own?
- How many funds are in my portfolio?
They are:
- How much of my portfolio depends on the largest holdings?
- How much overlap exists across my investments?
- Which sectors and economic themes drive my results?
- Is the position sizing appropriate for my retirement objectives and income needs?
- When should the portfolio be reviewed again?
A fiduciary investment adviser can help conduct this type of look-through review and evaluate whether your overall allocation remains aligned with your objectives. To request a portfolio or retirement-planning conversation with Portafolio Capital Management dba Mau Sanchez Capital, schedule a call with a fiduciary financial adviser or call (512) 593-8380.
Sources
- U.S. Securities and Exchange Commission, Investor.gov: Asset Allocation and Diversification
- FINRA: Concentration Risk
- S&P Dow Jones Indices: S&P U.S. Indices Methodology
- Portafolio Capital Management: Risk Analysis
- Portafolio Capital Management: Strategy
Portafolio Capital Management LLC dba Mau Sanchez Capital is a Texas-registered investment adviser. This content is provided for informational and educational purposes only and does not constitute personalized investment advice, tax advice, legal advice, or a solicitation to buy or sell any security. Investing involves risk, including the possible loss of principal. Advisory services are provided only pursuant to a written advisory agreement. Past performance is not indicative of future results.
Leave a Reply