
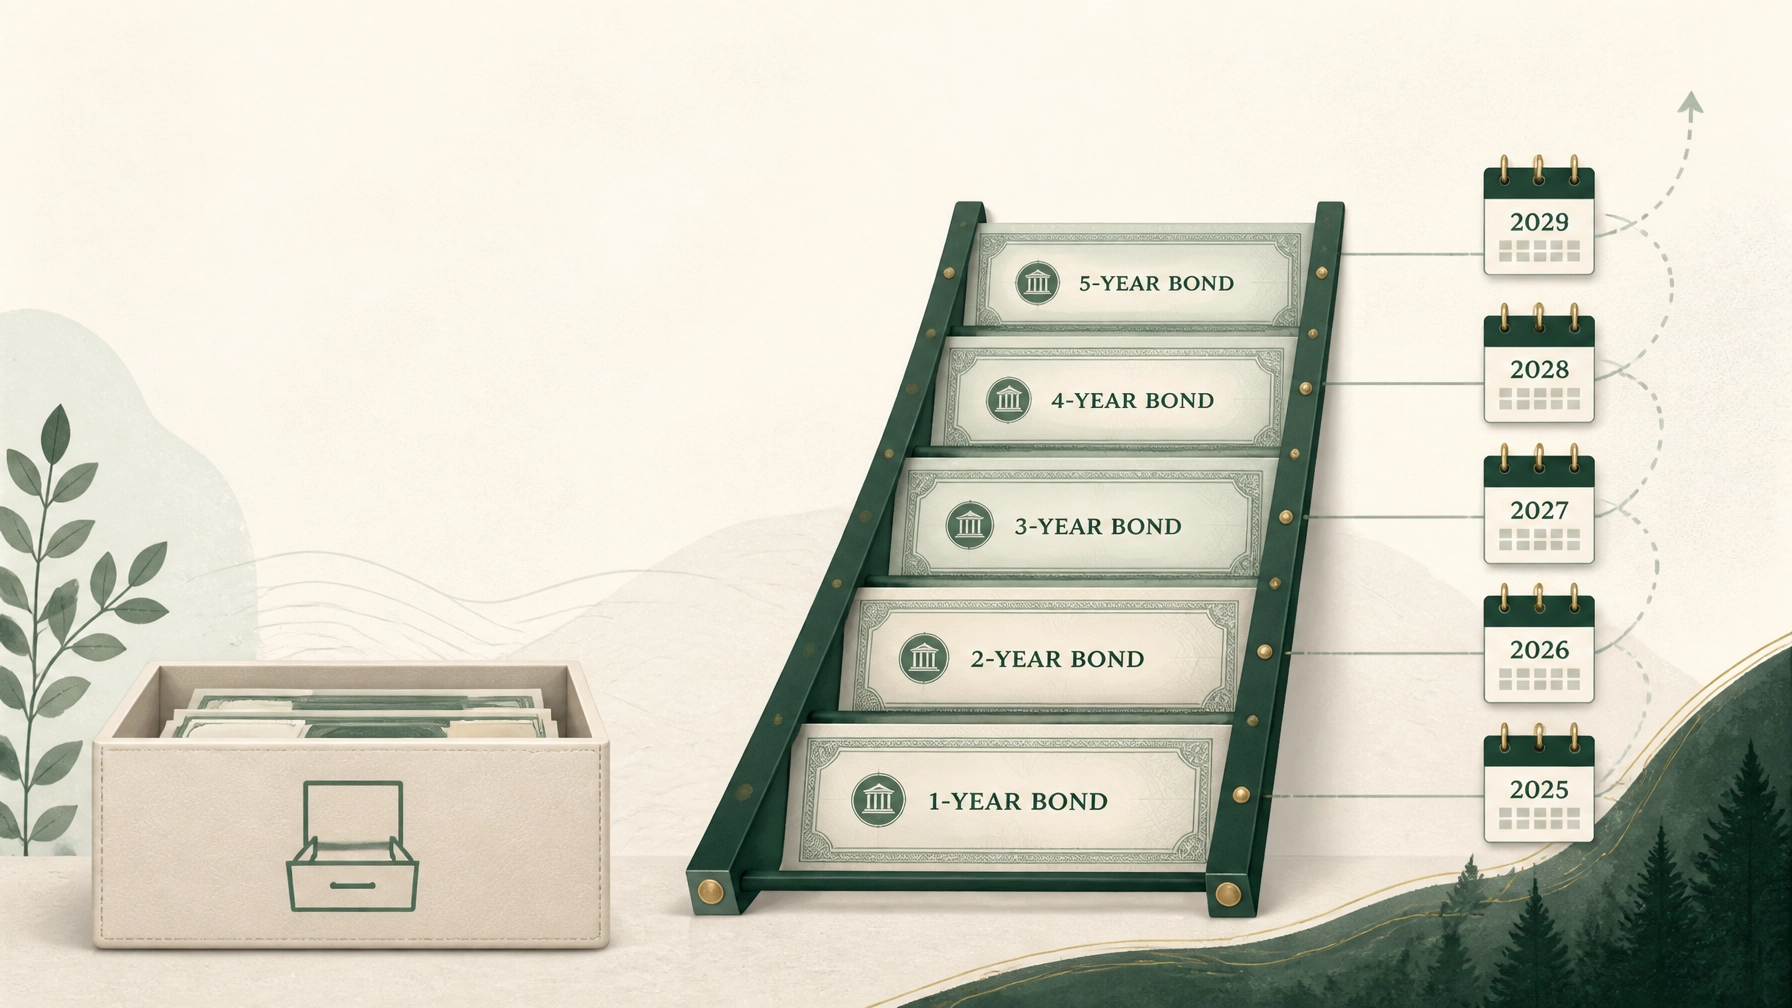
This illustration shows the difference between immediate cash access and a bond ladder designed around future maturity dates.
What is the difference between keeping money in a cash reserve and building a bond ladder?
Both approaches can play a role in a retirement plan, but they solve different problems. A cash reserve is designed for liquidity and short-term stability. A bond ladder is structured around a series of maturity dates, which can help coordinate future cash needs and reduce the risk of investing all available funds at one time.
The right comparison is not “cash versus bonds” in the abstract. It is a question of purpose:
- How soon might you need the money?
- Do you need immediate access, or can you wait for scheduled maturities?
- How important is it to lock in current yields?
- How much fluctuation could you tolerate if circumstances changed?
- How might inflation affect future purchasing power?
Understanding these differences can help you evaluate how each might fit into a broader retirement income and investment strategy.
What Is a Cash Reserve?
A cash reserve is money held for near-term spending, emergencies, unexpected expenses, or other needs where access and stability are more important than long-term growth.
Depending on the account or vehicle, a cash reserve may include:
- Bank checking or savings accounts
- Money market deposit accounts
- Money market funds
- Very short-term certificates of deposit
- Short-term Treasury bills
These options do not all have the same protections or mechanics. For example, FDIC insurance applies to eligible deposits at FDIC-insured banks, such as savings accounts, money market deposit accounts, and certificates of deposit. It does not apply to investment products such as bonds, bond funds, or money market mutual funds. The FDIC generally provides coverage of up to $250,000 per depositor, per ownership category, at each FDIC-insured bank. See the FDIC’s explanation of deposit insurance for details.
The main purpose of a cash reserve is not to maximize return. It is to provide a readily available source of funds without requiring you to sell longer-term investments at an inconvenient time.
What Is a Bond Ladder?
A bond ladder is a collection of individual bonds with staggered maturity dates. For example, a ladder might have bonds maturing in one, two, three, four, and five years.
As each bond matures, the principal can be used for planned spending or reinvested into a new bond, depending on the investor’s objectives. This creates a schedule of expected principal repayments rather than placing the entire amount into one maturity date.
A bond ladder may be built with different types of individual bonds. Each has its own credit, liquidity, call, and interest-rate considerations. U.S. Treasury securities, for example, are backed by the full faith and credit of the United States government, according to TreasuryDirect. Other bonds may involve additional issuer or credit risk.
A ladder is generally most useful when its maturity schedule is aligned with known future cash needs. It is not the same as a bond fund, where the fund generally continues buying and selling securities and does not have a fixed date when the entire portfolio matures.

The staggered rungs represent planned maturity dates, while the open reserve represents funds intended for more immediate access.
Bond Ladders and Cash Reserves: The Key Differences
1. Access to money
Cash reserves are generally intended to be accessible quickly. You can usually withdraw funds from a bank account or transact in a cash-oriented account without waiting for a specific maturity date.
A bond ladder provides planned access, not necessarily immediate access. If a bond has not matured and you need to sell it, the sale takes place at the current market price. That price may be higher or lower than the amount originally invested.
Bond prices generally move in the opposite direction of interest rates. If rates rise after a bond is purchased, the bond’s market value may decline. Selling before maturity could therefore result in a loss, particularly after considering transaction costs and the bond’s credit quality.
This is why money needed for emergencies or unpredictable expenses generally requires a different level of liquidity than money assigned to a known future date.
2. Maturity structure
Cash reserves typically have no required maturity date. You hold the money until you need it, and the balance may remain available from day to day.
A bond ladder is intentionally organized by maturity. Each rung has a defined date when the bond is scheduled to return its principal, assuming the issuer meets its obligations.
Treasury bills, for example, have short-term maturities of up to 52 weeks, while Treasury notes are issued with maturities ranging from two to ten years. TreasuryDirect explains the different types of Treasury marketable securities, including how they mature and how they may be sold before maturity.
The maturity schedule can be designed around future expenses, but it should not be treated as a substitute for an emergency reserve.
3. Reinvestment risk
Reinvestment risk is the possibility that future interest payments or maturing principal will need to be reinvested at lower interest rates.
Cash reserves experience this risk continuously. Their yields can adjust relatively quickly as short-term interest rates change. That can be helpful when rates rise, but it can also mean that income falls relatively quickly when rates decline.
A bond ladder spreads reinvestment across multiple dates. Instead of having the entire balance mature at one time, portions mature periodically. This may reduce the risk of having to reinvest a large amount under a single set of market conditions.
However, a ladder does not eliminate reinvestment risk. When a bond matures, available rates may be lower than the rate on the maturing bond. Coupon payments may also need to be reinvested at changing rates.
4. Interest-rate exposure
Cash reserves generally have limited price volatility because the underlying holdings are short-term or designed for stability. Their primary interest-rate risk is often related to changing income. The yield may rise or fall as market rates change.
Bond ladders can have more price sensitivity, especially when they include bonds with longer maturities. The longer a bond’s maturity and duration, the more its market price may respond to changes in interest rates. The Financial Industry Regulatory Authority provides an overview of bond risks and interest-rate sensitivity.
Holding an individual bond until maturity may reduce the importance of interim market-price changes for a specific spending goal. If the bond’s issuer remains able to pay and the bond is held to maturity, the investor generally receives the stated principal amount. But the economic value of the bond still changes, and the investor may face an opportunity cost if newer bonds offer higher rates.
5. Purchasing power
Both cash reserves and nominal bond ladders face inflation risk.
Inflation risk is the possibility that rising prices reduce what your money can buy in the future. A cash balance may remain stable in dollar terms while losing purchasing power if its yield remains below inflation.
A bond ladder may lock in known dollar payments, but those payments do not automatically increase with the cost of living. A fixed payment that seems adequate today may cover fewer goods and services several years from now.
For that reason, retirement planning needs to consider more than whether an account value is stable. It should also consider how income and assets may hold up against future expenses.

This illustration represents the planning value of aligning scheduled maturities with known future spending needs.
A Hypothetical Retirement Example
Consider a hypothetical couple, David and Elena, who are five years from retirement.
They expect to have irregular income during the first several years of retirement and want to maintain access to funds for healthcare costs, home repairs, and other unexpected expenses. They also have several known expenses they expect to pay over the next five years.
A cash reserve could help address the unpredictable expenses because the money remains readily available. A bond ladder could potentially be evaluated for the expenses with more certain timing, where the couple can wait for scheduled maturities rather than needing to sell investments immediately.
This example does not establish a universal allocation. The appropriate balance would depend on their total assets, income sources, spending needs, risk tolerance, and other factors. Readers with questions about tax implications should consult a qualified tax professional.
The broader lesson is that liquidity and maturity are different forms of flexibility. Cash provides flexibility about when money can be accessed. A bond ladder provides more structure around when principal is expected to become available.
Questions to Consider
Before evaluating either approach, consider the following:
- What is the time horizon? Money needed within months may require a different structure than money intended for expenses several years away.
- Are the expenses known or uncertain? A scheduled maturity may fit a known expense, while unpredictable costs require greater liquidity.
- Could you need to sell early? If so, understand that an individual bond’s market value may differ from its purchase price.
- How will maturities be managed? Someone must decide whether to spend the proceeds or reinvest them.
- What risks apply to the underlying holdings? Review credit quality, maturity, duration, call features, liquidity, and account protections.
- How could inflation affect the plan? Stable dollar values do not necessarily mean stable purchasing power.
- Is the overall portfolio properly diversified? Cash and bonds address certain risks, but they may not provide the long-term growth needed for a multi-decade retirement.
A fiduciary investment adviser can help evaluate these questions in the context of a broader portfolio rather than treating a cash reserve or bond ladder as a standalone solution. Portafolio Capital Management discusses its broader approach to portfolio construction and monitoring on its strategy page, while its risk analysis page explains why investment risk should be considered alongside a client’s objectives and time horizon.
The Bottom Line
Cash reserves and bond ladders are not interchangeable.
A cash reserve is primarily designed for immediate access, stability, and near-term needs. A bond ladder is structured around staggered maturities and may help coordinate planned future cash flows while spreading reinvestment decisions over time.
Both involve tradeoffs. Cash can lose purchasing power when inflation exceeds its yield. Bonds can fluctuate in value before maturity, and future payments may not keep pace with rising expenses.
The most useful starting point is to identify the purpose of each dollar, the date when it may be needed, and the amount of flexibility required. To discuss how liquidity, income needs, and portfolio risk fit together, schedule a conversation with a fiduciary financial adviser or call Portafolio Capital Management at (512) 593-8380.
Sources
- U.S. Treasury, About Treasury Marketable Securities
- FDIC, Understanding Deposit Insurance
- FINRA, Bond Basics and Risks
- Investor.gov, Bonds and Bond Funds

The final illustration emphasizes that a retirement portfolio may need both near-term liquidity and a structured plan for future cash needs.
Portafolio Capital Management LLC dba Mau Sanchez Capital is a Texas-registered investment adviser. This content is provided for informational and educational purposes only and does not constitute personalized investment advice, tax advice, legal advice, or a solicitation to buy or sell any security. Investing involves risk, including the possible loss of principal. Advisory services are provided only pursuant to a written advisory agreement. Past performance is not indicative of future results.
Leave a Reply