
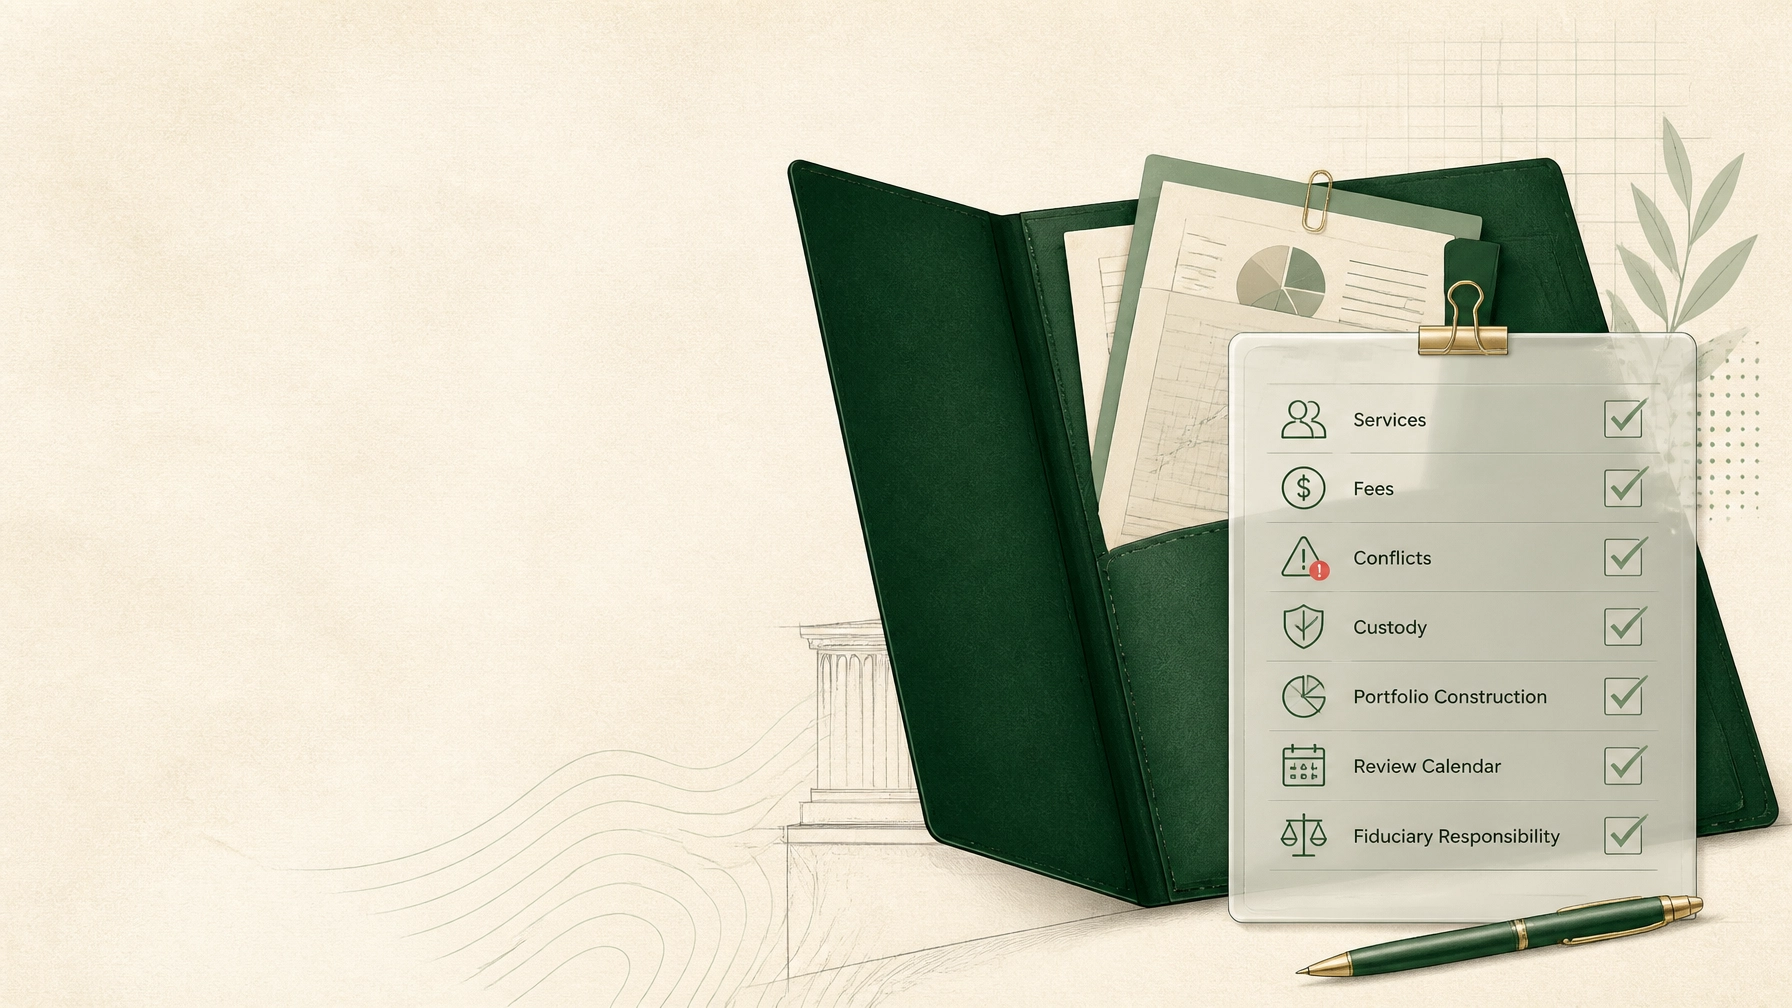
Description: An editorial financial illustration showing a transparent retirement portfolio review with service, cost, risk, and fiduciary checkpoints.
Choosing someone to manage your retirement portfolio is not simply a question of investment performance. Before any money is invested, you should understand what the adviser will do, how the relationship will work, what you will pay, and how potential conflicts will be handled.
A professional adviser should be willing to explain these details in plain English. You should not need to rely on vague promises, complicated language, or a generalized investment presentation.
This is not a comparison of adviser business models. It is a practical conversation guide for prospective clients who want to understand the relationship before entering into an advisory agreement.
1. What services are included?
The phrase “wealth management” can mean different things from one firm to another. Some advisers provide investment management only. Others may include retirement planning, cash-flow analysis, account coordination, or ongoing financial planning.
Ask the adviser to define the scope of service in specific terms:
- Will you provide portfolio management, retirement planning, or both?
- Will you help evaluate retirement income needs and general withdrawal considerations?
- Will you coordinate with my tax or legal professionals when appropriate?
- Will you manage all of my accounts or only certain investment accounts?
- Will I receive guidance when my circumstances change?
- What services are not included?
- Who will be responsible for communicating with me and answering questions?
The written advisory agreement should reflect the services discussed. If a service is important to your retirement plan, do not assume it is included simply because it was mentioned during an introductory meeting.
A clear scope of service also helps you understand whether you are paying for ongoing advice or a limited, one-time engagement.
2. How are fees calculated and collected?
Fees should be explained before an adviser manages your assets. You should understand both the adviser’s compensation and the other costs associated with your portfolio.
A common arrangement is an asset-based fee, which means the advisory fee is calculated as a percentage of the assets being managed. Other arrangements may involve fixed fees, hourly charges, or a combination of methods.
Ask questions such as:
- How is your advisory fee calculated?
- Is the fee based on the account balance, a flat amount, or another method?
- How often is the fee charged?
- Is the fee paid directly by me or deducted from my account?
- Are fees calculated before or after account values change?
- Are there minimum account sizes or minimum fees?
- What other costs may apply, including fund expenses, trading costs, or custody-related charges?
- Are any fees negotiable?
- Do you or anyone affiliated with the firm receive compensation from a specific investment or service?
The SEC’s Investor.gov guidance on Form ADV and Form CRS explains that investors should receive information about services, fees, conflicts, and disciplinary history. Form CRS, also known as Form ADV Part 3, is intended to provide a short, plain-English summary of the relationship.
An adviser should be able to show you an understandable estimate of your expected costs. You can also ask how the total cost of the relationship may affect your portfolio over time.
3. What conflicts of interest should you know about?
A conflict of interest exists when an adviser’s financial or business interests could influence the advice provided to a client. Conflicts do not always mean that advice is inappropriate, but they should be identified and explained.
Potential questions include:
- Do you receive compensation for recommending certain investments?
- Does the firm have proprietary investments or affiliated services?
- Are there incentives to recommend one account type over another?
- Could the firm earn more if I trade more frequently or invest in a particular product?
- Do relationships with third parties create additional compensation or business benefits?
- How are conflicts disclosed and monitored?
- What steps does the firm take to reduce or manage conflicts?
The SEC’s interpretation of an investment adviser’s fiduciary duty explains that the duty of loyalty requires an adviser not to subordinate a client’s interests to its own. Material conflicts should be fully and fairly disclosed in a way that allows the client to make an informed decision.
Be cautious of explanations that simply say, “We always act in your best interest,” without describing how the firm’s business practices support that standard.

Description: An original editorial illustration representing transparency between a client’s retirement goals and an adviser’s portfolio management process.
4. Who will hold and safeguard your assets?
Investment management and asset custody are separate functions. Custody refers to the institution that holds the assets, maintains the account, processes transactions, and provides account statements.
Ask:
- Will a separate qualified custodian hold my assets?
- Who will send my official account statements?
- How often will I receive statements?
- Can I verify advisory fees and transactions on the custodian’s statement?
- What authority will the adviser have over my account?
- Can the adviser withdraw money, or is authority limited to managing investments and deducting disclosed fees?
- What procedures are in place to prevent unauthorized transfers?
- How should I compare the custodian’s statements with the adviser’s reports?
You should know where your assets are held and which documents represent the official record of your account. An adviser should also explain how transactions, withdrawals, contributions, and fee deductions are handled.
The SEC’s Investor.gov investment professional search tool can help investors locate registration information and review available disclosures. This research does not replace a direct conversation, but it can help you prepare better questions.
5. How will the portfolio be constructed?
A portfolio should be connected to your retirement objectives, not built from a generic model alone.
Ask the adviser to explain:
- How do you determine an appropriate asset allocation?
- How do you evaluate my time horizon, income needs, and tolerance for volatility?
- How much of the portfolio may be allocated to stocks, bonds, cash, or other investments?
- How do you manage position size and concentration risk?
- How broadly will the portfolio be diversified?
- What role do liquidity and near-term spending needs play?
- How do you evaluate investment costs?
- What would cause you to change the portfolio?
- How do you distinguish between a temporary market decline and a change that requires action?
Asset allocation is the mix of investments held in a portfolio. It is one of the primary ways an investor manages the relationship between growth potential and investment risk.
Diversification means spreading investments across different companies, sectors, regions, or asset categories rather than relying heavily on one holding or one economic outcome. Diversification does not eliminate the possibility of loss, but it can reduce the impact of a single investment performing poorly.
A thoughtful adviser should be able to explain the reasoning behind the portfolio without presenting a market forecast as certain.

Description: An editorial financial illustration showing portfolio construction through asset allocation, risk review, diversification, and periodic monitoring.
6. How often will the portfolio be reviewed?
Ongoing portfolio management should have a defined process. “We monitor your account” is not specific enough by itself.
Ask:
- How often will we meet?
- How often is the portfolio formally reviewed?
- What events trigger a review outside the regular schedule?
- Will you contact me when market conditions change significantly?
- How will you respond if my retirement date changes?
- What happens if my spending needs increase?
- How are contributions, withdrawals, and cash needs incorporated?
- Who is responsible for updating my goals and financial information?
Your financial situation can change even when markets do not. A new retirement date, change in employment, inheritance, business sale, health concern, or shift in spending can affect how much portfolio risk is appropriate.
The review process should consider both investment performance and the broader retirement plan. A portfolio can be performing well while still being poorly aligned with an investor’s expected income needs or time horizon.
Portafolio Capital Management’s investment strategy overview describes the importance of aligning portfolio decisions with client objectives and maintaining appropriate oversight. The firm’s risk analysis resource provides another useful starting point for understanding how risk can be evaluated.
7. What does fiduciary responsibility mean in practice?
Fiduciary responsibility should be more than a label. It should influence how an adviser gathers information, evaluates options, explains costs, manages conflicts, and monitors the relationship.
The SEC describes an investment adviser’s fiduciary duty as including a duty of care and a duty of loyalty. In practical terms, that means an adviser should seek to understand your investment profile, provide advice based on your objectives, and avoid placing the adviser’s interests ahead of yours.
Ask:
- Will you act as a fiduciary throughout our advisory relationship?
- Does that responsibility apply to all services you provide?
- What information do you need from me before making recommendations?
- How do you evaluate risks, costs, and alternatives?
- How will you disclose material conflicts?
- What does ongoing monitoring include?
- Where can I read the firm’s Form ADV and Form CRS?
A fiduciary relationship does not eliminate investment risk or guarantee a particular outcome. It also does not mean every recommendation will be profitable. It establishes an important standard for how advice should be provided and how the relationship should be managed.
A practical example
Consider a hypothetical couple who are five years from retirement. They have several accounts, a concentrated position in their employer’s stock, and uncertainty about how their portfolio may support retirement spending over time.
Before hiring an adviser, they should ask:
- Will the adviser review the entire household portfolio or only one account?
- How will concentration in employer stock be evaluated?
- What fees will apply to each account?
- Who will hold the assets and send statements?
- How will the portfolio be reviewed as retirement approaches?
- What services are included if their income needs or retirement date change?
- What conflicts could affect the recommendations?
These questions help the couple evaluate the relationship itself before debating individual investments. Questions involving tax consequences, tax planning, or account-specific tax decisions should be reviewed with a qualified tax professional based on the household’s individual circumstances.
The goal is clarity before commitment
A strong initial conversation should leave you with a clearer understanding of the adviser’s role, the total cost of the relationship, the handling of conflicts, the custody arrangement, the investment process, and the review schedule.
You should also feel comfortable asking follow-up questions. Retirement portfolios often support decades of future spending, so the relationship guiding those assets deserves careful attention. If you have questions about how tax rules may apply to your situation, consult a qualified tax professional.
If you would like to discuss your retirement portfolio, investment strategy, or ongoing portfolio oversight, schedule a conversation with Portafolio Capital Management dba Mau Sanchez Capital. You can also learn more at portafoliocapital.com or call (512) 593-8380.
Portafolio Capital Management LLC dba Mau Sanchez Capital is a Texas-registered investment adviser. This content is provided for informational and educational purposes only and does not constitute personalized investment advice, tax advice, legal advice, or a solicitation to buy or sell any security. Investing involves risk, including the possible loss of principal. Advisory services are provided only pursuant to a written advisory agreement. Past performance is not indicative of future results.
Leave a Reply